A salaried employee earning ₹80,000 a month has roughly ₹9,600 landing in their EPF account every month without lifting a finger, matched by an equal contribution from the employer. A freelancer billing the same ₹80,000 has nothing going toward retirement unless they set it up themselves. No HR system deducts it. No employer tops it up. No reminder email nudges them on the 1st of the month.
That single difference changes the entire shape of retirement planning for freelancers in India. It isn’t about picking better investments than a salaried person. It’s about building, from scratch, the structure that a salaried person gets for free. This guide walks through what that structure should look like, instrument by instrument.
What Exactly Does a Salaried Employee Get That a Freelancer Doesn’t?
Three things quietly work in the background of every salaried paycheck, and all three disappear the moment someone goes independent.
- EPF (Employees’ Provident Fund): The employee contributes 12% of basic salary and dearness allowance every month, and the employer matches it with an equal 12%, part of which is diverted into a pension component. It is a forced, automatic savings habit backed by a government-mandated match.
- EPS (Employees’ Pension Scheme): A portion of the employer’s contribution builds toward a modest monthly pension after retirement, on top of whatever the employee has separately invested.
- Gratuity: A lump sum paid by the employer after five years of continuous service, calculated on the employee’s last drawn salary. It functions as an unplanned retirement cushion that nobody has to think about until it arrives.
A freelancer starts from zero on all three. There is no forced contribution, no employer match, and no gratuity waiting at the end. Retirement planning for freelancers in India has to replace the discipline these systems impose, not just their investment value.
How Much Should a Freelancer Actually Save for Retirement Each Month?
A fixed rupee target doesn’t work well here, because freelance income moves around from month to month. A percentage of billings is a more practical anchor.
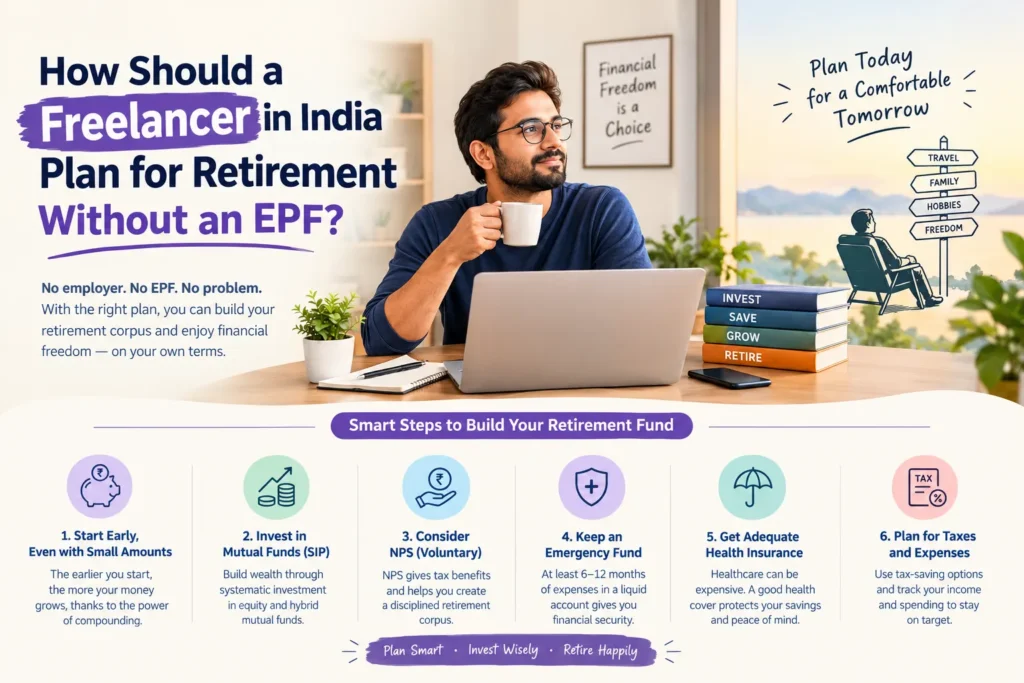
A reasonable starting range is 15–20% of monthly income directed toward retirement, separate from any emergency fund or short-term goals. In a strong month, that percentage can rise. In a lean month, it can shrink, but it shouldn’t disappear entirely, because restarting a stopped habit is far harder than scaling down a running one.
This is one of the clearest differences in retirement planning for freelancers in India compared with salaried employees: the contribution has to flex with income, because there’s no fixed salary to calculate a fixed percentage against.
NPS vs PPF vs Mutual Fund SIPs: Which Should Replace Your EPF?
No single instrument does what EPF used to do. For retirement planning for freelancers in India to actually work, the role has to be split across three.
NPS (National Pension System): This is the closest structural substitute, because it’s a dedicated retirement account that locks in until age 60, just like EPF did. A freelancer can open a Tier 1 NPS account individually through any point of presence or the eNPS portal, choose Active Choice, and allocate up to 75% to equity until age 50, after which the equity cap tapers. At retirement, 60% of the corpus can be withdrawn tax-free, while the remaining 40% must go into an annuity that pays a taxable pension.
PPF (Public Provident Fund): This plays the role EPF’s debt component used to play; a guaranteed, government-backed return with no market exposure, currently 7.1% per annum, reviewed by the government every quarter. Interest and maturity proceeds are entirely tax-free. The 15-year lock-in (extendable in blocks of five years) suits retirement money well, since it discourages withdrawal before the money is actually needed.
Equity mutual fund SIPs: Neither NPS nor PPF alone will outpace inflation comfortably over a 25–30 year horizon on their own, which is where equity SIPs come in as the growth engine. Unlike NPS and PPF, SIPs carry no lock-in, which cuts both ways: more flexibility, but also more temptation to dip into retirement money for something else.
The tax angle that catches most freelancers off guard
Under the old tax regime, a self-employed individual can claim a deduction of up to 20% of gross total income for NPS contributions under Section 80CCD(1), within the overall ₹1.5 lakh Section 80C limit, plus an additional ₹50,000 under Section 80CCD(1B). Under the new tax regime, neither of these deductions is available, and since a freelancer has no employer, there’s no employer-contribution deduction to fall back on either. A freelancer who has defaulted into the new regime gets zero tax benefit from their own NPS contribution. That doesn’t make NPS a bad choice, but it does mean the decision should be made on asset allocation and discipline, not on a tax deduction that may not apply.
How Do You Keep Saving Consistent When Your Income Isn’t?
This is the behavioural problem salaried retirement planning never has to solve, and it’s arguably more important than which instrument gets chosen.
- Automate a percentage, not a fixed amount. A standing instruction for a fixed SIP amount will bounce in a lean month and quietly get skipped. A percentage-based transfer, moved manually at the start of each month once an invoice is paid, survives income swings better.
- Build the emergency fund before scaling up retirement contributions. Three to six months of expenses sitting in a liquid fund or sweep-in deposit means a slow quarter doesn’t force a freelancer to stop retirement investing or, worse, withdraw from it.
- Treat retirement savings as a bill, not a leftover. Paying it first out of every invoice, before discretionary spending, keeps the percentage honest even when the temptation to skip it is strongest.
At Techolic, this is usually the first thing we help freelance clients fix. Most already know roughly which instruments they should be using. What’s missing is a system that keeps contributions flowing when income doesn’t arrive on a predictable schedule.
What About Gratuity and EPS? Is There Any Substitute?
Not a direct one-for-one replacement, but the two jobs they quietly did can be covered separately.
Gratuity functions as an unplanned lump-sum cushion, usually needed if someone is unable to work due to illness, disability, or death before retirement. A term insurance policy covers exactly that gap, at a fraction of what an endowment or whole-life policy would cost for the same cover. EPS provided a modest guaranteed pension; a slightly larger PPF allocation, or the mandatory 40% NPS annuity at retirement, covers a similar role, even if the mechanics differ.
What Mistakes Do Freelancers Commonly Make With Retirement Planning?
These are the errors that come up most often when freelancers approach retirement planning for the first time without the EPF default to lean on.
- Treating ELSS as the whole retirement plan. ELSS mutual funds save tax under Section 80C with just a three-year lock-in, which makes them an easy default. But three years is a tax-saving horizon, not a retirement horizon, and ELSS alone won’t build the discipline or the debt-equity balance that a real retirement plan needs.
- Stopping contributions entirely in a lean month. Scaling down is normal. Stopping altogether breaks the habit, and restarting it after a few months of silence is far harder than most freelancers expect.
- Choosing the new tax regime without checking what it costs on NPS. As covered above, the ₹50,000 extra deduction and the 20%-of-income deduction both disappear under the new regime. That’s a reasonable trade-off for some freelancers, but it should be a conscious one.
- Ignoring health insurance as part of the retirement plan. A salaried employee’s group health cover disappears the day they quit the job. A freelancer needs to self-fund a health policy now and keep funding it into retirement, since a single hospitalisation late in life can undo years of retirement saving.
- Forgetting to update nominee details. NPS, PPF and mutual fund folios all need nominees, and this step is easy to skip when there’s no HR department running annual compliance checks.
What Does a Sample Retirement Savings Split Look Like for a Freelancer?
One illustrative way to divide a monthly retirement allocation, assuming a freelancer in their early 30s with a reasonable risk appetite, might look like this. These are illustrative assumptions to show how the pieces fit together, not a formula to copy without adjusting for your own income, age and risk tolerance.
40% to equity mutual fund SIPs — the long-term growth component, with the flexibility to increase contributions in strong months.
35% to NPS — split between equity and debt within the account, locked in until 60, acting as the core retirement-specific vehicle.
25% to PPF — the guaranteed, tax-free anchor that balances out the market exposure in the other two.
The exact split should shift with age, tilting toward NPS and PPF as retirement gets closer, in the same way a salaried employee’s EPF balance naturally grows more conservative over a career.
Can a Freelancer Open an NPS Account Without an Employer?
Yes. Freelancers and self-employed individuals open NPS Tier 1 accounts individually, through:
- The eNPS portal, using Aadhaar-based e-KYC
- Any bank or financial institution registered as a Point of Presence (PoP)
- Most major broking and investment platforms that now offer NPS onboarding
No employer registration or sponsorship is required. The account is entirely in the individual’s name, and contributions can be made at any frequency, including irregular, income-driven top-ups.
Is Retirement Planning for Freelancers in India Really That Different from Salaried Planning?
The instruments are largely the same. What’s different is who’s responsible for making them work. A salaried employee’s EPF runs quietly in the background regardless of discipline. A freelancer’s NPS, PPF and SIP contributions only happen if the freelancer makes them happen, every single month, without a payroll system forcing the habit. That’s the real shift retirement planning for freelancers in India demands: building a personal system that does the job an employer used to do automatically.
If structuring this feels like one more thing to manage alongside client work and invoicing, the Techolic team can help map out a contribution plan that fits an irregular income pattern rather than fighting it.
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. NPS returns are market-linked and not guaranteed. The percentages and splits in this article are illustrative and not personalised financial advice.
Frequently Asked Questions
Can a freelancer open an NPS account without an employer?
Yes. NPS Tier 1 accounts can be opened individually through the eNPS portal, a registered Point of Presence, or most investment platforms, with no employer involvement needed at any stage.
Is NPS or PPF better for a freelancer’s retirement?
They serve different roles rather than competing with each other. NPS allows equity exposure and functions as the dedicated retirement account; PPF offers a guaranteed, tax-free return as the safer anchor. Most freelancers benefit from holding both rather than choosing one over the other.
How much should a freelancer save for retirement each month?
A commonly used starting range is 15–20% of monthly income, treated as a percentage of billings rather than a fixed rupee amount, so it can flex with the freelancer’s actual earnings.
What happens to retirement savings during a slow income month?
The contribution can be scaled down, but it shouldn’t stop altogether. A smaller SIP or NPS contribution in a lean month keeps the habit alive, which matters more over a 25–30 year horizon than hitting an exact percentage every single month.
Does a freelancer need life insurance as part of retirement planning?
A term insurance policy is worth considering, since it covers the lump-sum protection role that gratuity provides for salaried employees, at a relatively low premium for pure risk cover.
Does the new tax regime affect NPS benefits for freelancers?
Yes. Under the new tax regime, a freelancer cannot claim the Section 80CCD(1) or Section 80CCD(1B) deductions on their own NPS contributions, since those are available only under the old regime and there’s no employer contribution to claim separately. This doesn’t change NPS’s value as an investment, but it does remove the tax-saving reason some freelancers choose it.