Open any mutual fund app and the first thing it shows you is a returns table. 1 year, 3 years, 5 years, sorted from highest to lowest. It looks like the homework is already done: pick the fund at the top, start a SIP, get on with your day. Most of us have done exactly that at least once.
Here’s the catch. That table tells you what a fund earned, but not how it earned it. Did the manager do something clever, or did the whole market simply have a good year? And how wild was the ride you would have had to sit through to get that number? Two small Greek letters answer those questions. Alpha and beta in mutual funds are the numbers that separate a genuinely well-run fund from one that was lucky or just took on a lot of risk. It is worth the effort, too: S&P’s SPIVA India Scorecard keeps finding that most active funds trail their benchmark over ten years, and its mid-2026 edition showed more than 70% doing so in every category it covers.
No maths degree needed. In this guide, we walk through what a mutual fund is and why raw returns mislead, what alpha and beta mean with worked rupee examples, whether high alpha is always good, whether high beta is good or bad, and a practical step-by-step way to use both numbers when you choose a fund.
What is a mutual fund, and why do we need alpha and beta to judge one?
A mutual fund pools money from many investors and hands it to a professional fund manager, who invests it in stocks, bonds or other assets according to the scheme’s stated objective. The structure is regulated by SEBI, and every scheme declares a benchmark, an index such as the Nifty 50 TRI or Nifty 500 TRI, against which its performance is measured.
That benchmark is the key to everything in this article. A fund that returned 18% in a year sounds impressive until you learn that its benchmark returned 22%. A fund that returned 6% sounds weak until you learn that its benchmark returned 1%. Returns only make sense relative to the market and relative to risk.
Two questions sit behind every fund comparison:
- How much did the fund move with the market? That is beta, and it tells you whether the fund suits your risk appetite.
- Did the manager deliver anything beyond that movement? That is alpha, and it tells you whether you are getting value for the fee you pay.
So the role of beta in fund selection is to check suitability, and the role of alpha is to check skill. A fund can pass one test and fail the other, which is exactly why you need both.
What do alpha and beta in mutual funds actually measure?
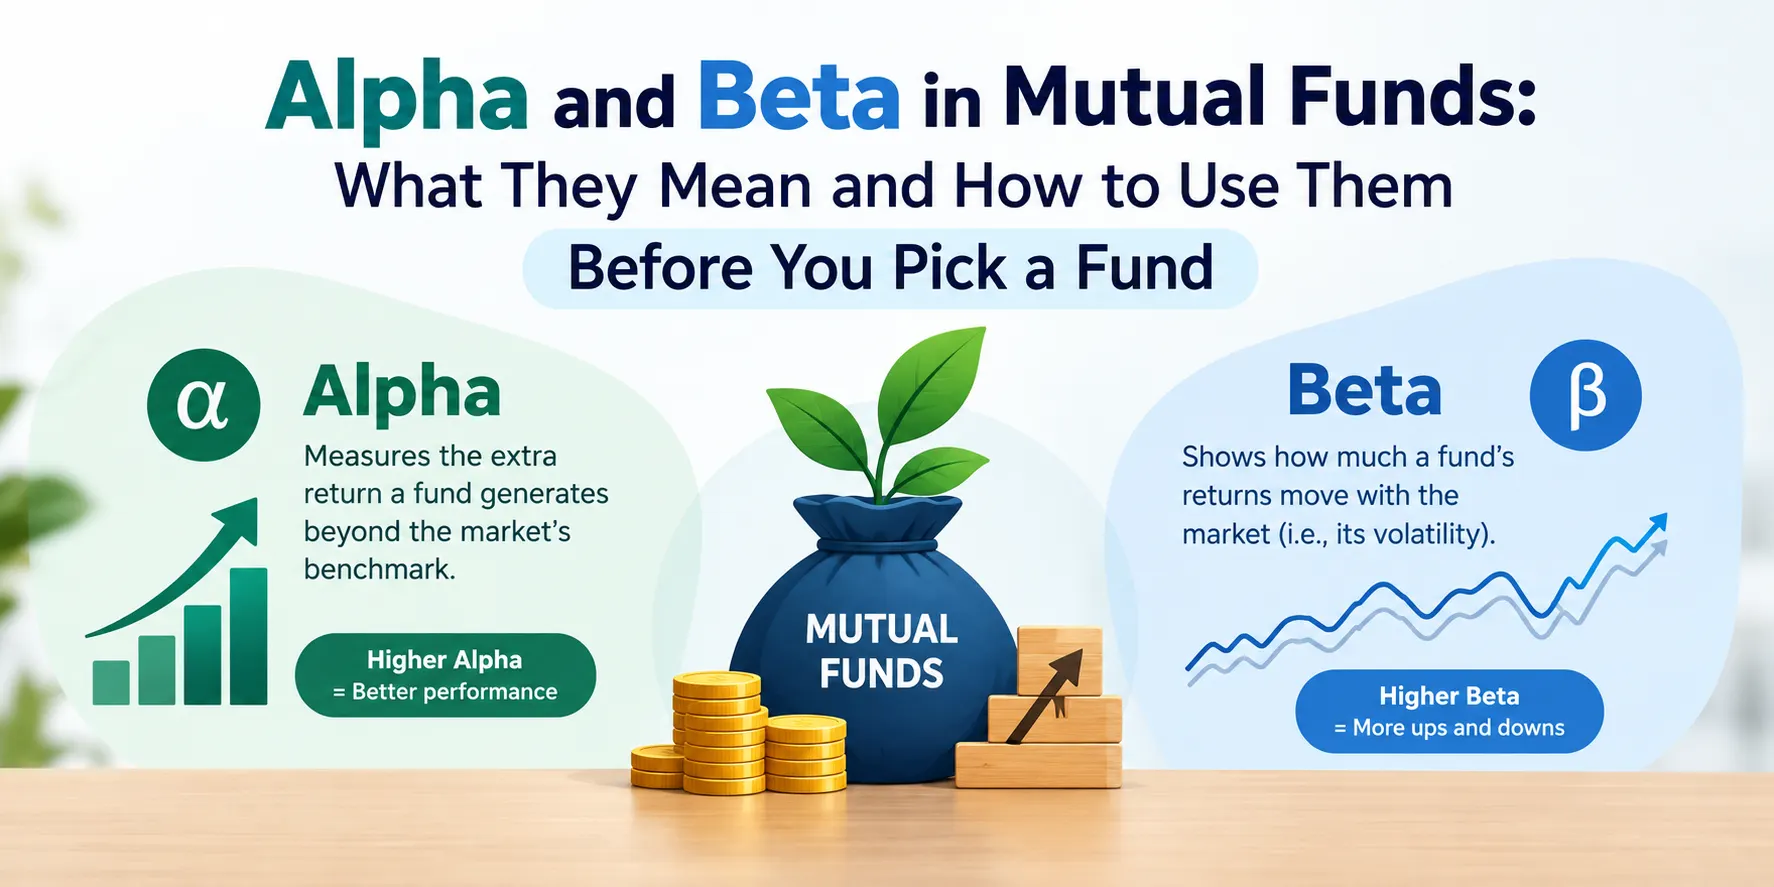
Think of the market as the tide. When the tide rises, almost every boat rises with it. Beta measures how strongly your boat responds to the tide. Alpha measures how much further the rower got beyond what the tide carried the boat.
Beta: The sensitivity of a fund’s returns to its benchmark. The benchmark itself has a beta of 1.
Alpha: The return a fund earned above (or below) what its beta and the market’s return would have predicted. It is the manager’s contribution after adjusting for risk.
Both numbers come from comparing a fund’s past returns with its benchmark’s past returns, usually over the trailing three years, though data providers differ on the exact window. They are statistical estimates of history, not promises about the future. Keep that in mind as we go.
What is beta in a mutual fund?
Beta is the slope of a line. Plot the fund’s periodic returns against the benchmark’s returns over the same periods, fit a line through the points, and the slope of that line is beta. You do not need to calculate it yourself, since factsheets and research platforms publish it, but you do need to read it correctly.
How do you read beta values?
Beta of 1: The fund has historically moved in line with its benchmark. If the benchmark rose 10%, the fund rose roughly 10%.
Beta above 1: The fund amplifies market moves in both directions. A beta of 1.2 means roughly 12% for every 10% in the benchmark, up or down.
Beta below 1: The fund moves less than the market. A beta of 0.8 means roughly 8% for every 10% in the benchmark, again in both directions.
Notice the phrase “in both directions”. Beta does not distinguish between good volatility and bad volatility. It is symmetrical.
What does beta look like in rupees?
Here is an illustration with assumed numbers. Say you hold ₹10 lakh in each of two funds, one with a beta of 1.2 and one with a beta of 0.8, both measured against the same benchmark.
- If the benchmark rises 15%: the first fund would be expected to gain about 18% (₹11.8 lakh) and the second about 12% (₹11.2 lakh).
- If the benchmark falls 20%: the first would be expected to fall about 24% (₹7.6 lakh) and the second about 16% (₹8.4 lakh).
Illustrative example: These figures are assumptions to show the mechanics, not forecasts. Real funds will deviate because beta is estimated from past data, and a fund’s actual stocks and the manager’s decisions also affect the outcome.
The gap between ₹7.6 lakh and ₹8.4 lakh is the real-world meaning of beta. It is the difference that decides whether you stay invested through a bad year or panic and stop your SIP.
Why does the benchmark change the beta?
Beta is always “beta against something”. The same small-cap fund can show a beta well above 1 when measured against the Nifty 50 and a beta close to 1 when measured against a small-cap index. This is why you should only compare beta figures that use the fund’s own declared benchmark, or at least the same benchmark across the funds you are comparing.
What does beta not tell you?
- It says nothing about whether the fund’s risk came from the market or from a few risky stock bets the manager made.
- It treats upside and downside swings as equal, although you only worry about one of them.
- It is calculated from history. A fund whose manager changed strategy last year may have a beta that no longer describes it.
- It is only meaningful when the benchmark actually explains the fund’s movements, which is what R-squared tells you (more on that shortly).
What is alpha in a mutual fund?
Alpha is the excess return a fund generated after accounting for the risk it took. The standard measure, called Jensen’s alpha, uses this formula:
Alpha = Fund return − [Risk-free rate + Beta × (Benchmark return − Risk-free rate)]
The part in square brackets is the return you should have expected given the fund’s beta. Whatever the fund earned beyond that is alpha. If the fund earned less, alpha is negative.
How do you calculate alpha with a simple example?
Take two equity funds and assume a risk-free rate of 6.5% and a benchmark return of 12% for the period. These are illustrative numbers.
Fund A: Beta 0.9, return 12.5%. Expected return = 6.5 + 0.9 × (12 − 6.5) = 11.45%. Alpha = 12.5 − 11.45 = +1.05%.
Fund B: Beta 1.3, return 14%. Expected return = 6.5 + 1.3 × (12 − 6.5) = 13.65%. Alpha = 14 − 13.65 = +0.35%.
Fund B posted the higher raw return, so it would top a simple returns table. But it also carried 30% more market sensitivity, and most of its extra return was simply the reward for taking that risk. Fund A’s manager added more value on a risk-adjusted basis. This is the single most useful lesson alpha teaches: a higher return is not the same as better management.
Is alpha the same as “excess return over the benchmark”?
Not quite, and this trips up many investors. Several apps and websites show “alpha” as plain fund return minus benchmark return, which ignores beta and the risk-free rate entirely. True Jensen’s alpha adjusts for both. The two numbers can differ noticeably, especially for high-beta or low-beta funds. When you see an alpha figure, check how the platform defines it, and always compare funds using the same source.
Why does the TRI benchmark matter for alpha?
Since 1 February 2018, SEBI has required mutual funds to compare performance against the Total Return Index (TRI) of their benchmark, which includes reinvested dividends, instead of the price-return index. This matters because a price index understates what the market actually delivered, and a fund measured against it looks better than it is. If you ever see an alpha calculated against a price index, it is flattered by roughly the index’s dividend yield.
Is alpha measured before or after fund costs?
After. A fund’s NAV already has the expense ratio deducted, so the alpha you see is what remains once the AMC has taken its fee. This is also why the same scheme’s regular plan, which carries a higher expense ratio because of distribution commission, will show a lower alpha than its direct plan, even though the portfolio is identical.
What is the difference between alpha and beta?
What it measures: Beta measures risk relative to the market. Alpha measures value added by the manager after adjusting for that risk.
Question it answers: Beta asks, “How bumpy will this ride be?” Alpha asks, “Is the driver worth paying for?”
Who controls it: Beta is largely a result of the portfolio’s construction and category, so you choose it when you choose the fund. Alpha depends on the manager’s decisions and is far harder to sustain.
What you want: There is no universally ideal beta, only one that matches your risk tolerance and horizon. For alpha, consistently positive is the goal.
How stable it is: Beta tends to be fairly stable for a given strategy. Alpha changes a lot from one period to the next.
Is high alpha good in a mutual fund?
Generally yes, but only when the alpha is earned, repeatable and measured properly. A high alpha figure on a screen is a starting point for questions, not an answer. Here is where it can mislead you.
- It came from one lucky stretch. A strong alpha over twelve months, often during a small-cap or mid-cap rally, says very little. A modest alpha that shows up in the 3-year, 5-year and 7-year figures says much more.
- The benchmark is the wrong yardstick. A flexi-cap fund holding a lot of mid and small caps, measured against the Nifty 50, will look brilliant in a broad rally. That is extra risk showing up as extra return, which is beta wearing alpha’s costume.
- R-squared is low. If the benchmark explains only a small part of the fund’s movements, both alpha and beta are unreliable estimates. As a rough rule, be cautious when R-squared falls well below 70 or so.
- The portfolio is concentrated. A fund built on a handful of big bets can post huge alpha when they work and deep losses when they do not. Check the top holdings and the worst drawdown, not just alpha.
- The manager who earned it has left. Alpha belongs to a process and a person. If the fund manager changed recently, the track record may no longer describe the fund you would actually be buying.
- The fund has grown too big. In mid-cap and small-cap funds especially, a swelling fund size makes it harder to build meaningful positions in smaller stocks, and alpha often fades.
A simple test: A fund with 1.5% alpha that holds up across seven years is usually a better bet than a fund with 5% alpha in a single year. Consistency is the quality you are really paying for. (Illustrative comparison, not a rule of thumb for any specific fund.)
What does negative alpha mean?
It means the fund delivered less than its risk level justified. A few months of negative alpha are normal for any active fund. Persistent negative alpha across five years or more is a sign that you are paying an active management fee without receiving active management value. At that point, a low-cost index fund is worth a serious look.
Is a high beta good or bad in a mutual fund?
Neither. A high beta is a feature, and whether it helps depends on your horizon, your goal and your temperament.
When high beta works for you: You are investing for ten years or more, you are doing a monthly SIP, and you have the stomach to watch your portfolio fall 25% to 30% without selling. In a long rising market, a higher beta can compound faster.
When high beta hurts you: You need the money in two or three years, such as for a child’s admission fee or a down payment, or you know that a deep fall would push you to stop investing. A fund that drops 30% right before you need the money does not get a second chance to recover.
When low beta works for you: You are close to a goal, you are a new investor building comfort with equity, or you want a cushion in the portfolio.
When low beta disappoints: In a strong bull run, a low-beta fund will lag, sometimes sharply. And check why the beta is low. If it comes from holding a large cash pile, you are paying equity fund fees for money sitting idle.
Does a high beta fund deserve credit for strong returns?
Only partly. In a rising market, a high-beta fund will beat a low-beta fund almost automatically, with no special skill involved. This is why a fund’s return in a bull year says little about its manager. Judge the manager by alpha, and judge the fund’s fit for you by beta.
Do SIP investors benefit from high beta?
SIPs do reduce the impact of volatility, because you buy more units when prices fall. But that does not mean you should pick the highest-beta fund available. A SIP only works if you stay with it. If a high-beta fund’s swings are large enough to make you pause your SIP in a downturn, you lose the very benefit that rupee-cost averaging offers.
Can a fund have high alpha and high beta together?
Yes, and the combination you land in tells you a lot.
High alpha, low or moderate beta: The ideal, and the rarest. The manager is adding value without loading you with extra market risk. Verify that it is sustained before you get excited.
High alpha, high beta: Could be real skill, or could be a bull market flattering a risky portfolio. Check R-squared, downside capture and how the fund behaved in the last market fall.
Low alpha, high beta: The worst quadrant. You are taking extra risk and not being paid for it. There is rarely a reason to hold such a fund.
Low alpha, low beta: A defensive fund that adds little beyond the market. It may suit a conservative investor, but compare it with an index fund or a hybrid fund that does the same job more cheaply.
Which other ratios should you read alongside alpha and beta?
Alpha and beta are strongest when they are cross-checked. These are the companions worth looking at in the same factsheet or research page:
- R-squared: Shows how much of the fund’s movement the benchmark explains, on a scale of 0 to 100. A low value means alpha and beta are shaky.
- Standard deviation: Measures the total volatility of the fund’s returns, including the part that has nothing to do with the market.
- Sharpe ratio: Return earned per unit of total risk. Higher is better, and it is useful for ranking funds within a category.
- Sortino ratio: Like Sharpe, but it only counts downside volatility, which is closer to how investors actually feel risk.
- Upside and downside capture ratio: Shows what share of the benchmark’s rises and falls the fund captured. A fund that captures 95% of the upside and 80% of the downside is doing something right, and beta alone cannot show you that.
- Tracking error: Mainly for index funds. Shows how closely the fund follows its index.
- Maximum drawdown and rolling returns: Show the worst fall and how consistent returns were across different start dates.
Remember that SEBI’s riskometer, which grades schemes on six levels from Low to Very High, is a separate classification. It is a useful first filter for suitability, but it is not a substitute for reading the numbers above.
How do you use alpha and beta in mutual funds while choosing a fund?
This is the sequence we follow at Techolic when a client wants to compare funds. It works for beginners and experienced investors alike.
- Start with the goal and the horizon. Decide how many years you have and how big a fall you can live with. If seeing ₹10 lakh become ₹7 lakh would make you stop investing, you are not a high-beta investor, whatever the past returns say.
- Pick the category first. Compare large-cap with large-cap, flexi-cap with flexi-cap. Alpha and beta numbers across categories are not comparable because the benchmarks and risk levels are different.
- Check the benchmark. Make sure it is appropriate for what the fund actually holds, and that performance is shown against the TRI version.
- Read beta against category peers. A large-cap fund with a beta far above its peers is taking on risk you may not expect from the label.
- Look at alpha over several windows. Check the 3-year, 5-year and, where available, 7-year or 10-year figures, plus rolling returns. One strong year should never decide the matter.
- Cross-check with R-squared, Sharpe, Sortino and downside capture. If these disagree with alpha, trust the caution.
- Look under the hood. Check the manager’s tenure, the size of the fund, how concentrated the portfolio is and the expense ratio. Prefer the direct plan unless you are paying for advice you value.
- Decide the fund’s role in your portfolio. Many investors do well with a core of low-cost, beta-of-about-1 index or large-cap exposure and a smaller satellite of active funds with a proven alpha record.
We never treat alpha as a reason to buy on its own. A fund earns a place in a portfolio when its beta fits your goal, its alpha has held up across market cycles, and its cost is reasonable. That is the standard we apply when we review a portfolio, and it is the one we encourage readers to apply to their own.
Quick checklist before you invest: Is the beta comfortable for my horizon? Is alpha positive across 3 and 5 years? Is R-squared high enough to trust the numbers? Did the fund hold up in the last major fall? Is the expense ratio fair for what I get?
Where can you find the alpha and beta of a mutual fund?
You have three practical options. Most AMC monthly factsheets carry standard deviation, beta and Sharpe ratio for equity schemes, and some include alpha as well. Fund research platforms such as Value Research and Morningstar India publish alpha, beta, R-squared and capture ratios in one place. And the scheme’s website page for each fund usually links the latest factsheet.
One caution before you start comparing. The same fund can show different alpha and beta figures on different platforms, because providers use different time periods, return frequencies (daily, weekly or monthly), benchmarks and risk-free rates. Pull your numbers for all candidates from the same source and the same period. For alpha and beta in mutual funds, an apples-to-apples comparison matters more than the exact decimal.
Do alpha and beta work for debt, index and hybrid funds?
They are designed for equity funds, and they fit some other categories less well.
Debt and liquid funds: Beta and alpha are not meaningful here, because bond returns do not move with an equity index. Look at yield to maturity, modified duration, credit quality and the expense ratio instead.
Index funds and ETFs: Beta is close to 1 by design, and alpha will be near zero or slightly negative, roughly equal to the fund’s costs and tracking error. Tracking error and expense ratio are the numbers that separate one index fund from another.
Hybrid funds: These can be read with caution, but only against a benchmark that matches their blend of equity and debt. A hybrid fund compared with a pure equity index will show a misleadingly low beta.
Arbitrage funds: Equity-style beta and alpha do not describe how they work. Judge them on returns, taxation and costs.
A note on “smart beta”: You may see factor-based index funds described as smart beta, such as low-volatility or momentum indices. There, “beta” refers to exposure to a rules-based factor index, not the statistical measure we have discussed in this article.
What are the common mistakes investors make with alpha and beta in mutual funds?
- Chasing last year’s alpha. One strong year, often in a rally, tells you very little about the next five.
- Comparing across categories. A small-cap fund’s beta or alpha cannot be compared with a large-cap fund’s. Their benchmarks differ.
- Ignoring the benchmark. Alpha is only as honest as the yardstick it is measured against.
- Mistaking high beta for skill. A fund that rose 40% in a bull run may simply have been the most aggressive one.
- Assuming low beta means no loss. A beta of 0.7 still means the fund will fall when the market falls.
- Treating the numbers as forecasts. Alpha and beta describe the past, and a change in manager or strategy can make them obsolete.
- Mixing data sources. Taking beta from one site and alpha from another makes the comparison unreliable.
- Skipping R-squared. A confident-looking alpha with a low R-squared is mostly noise.
- Overlooking costs and plan type. The regular plan’s higher expense ratio quietly eats into alpha every year.
- Applying them to debt funds. The numbers exist on some screens, but they carry no useful meaning for bond funds.
What are the pros and cons of relying on alpha and beta?
Pros: They convert vague impressions such as “this fund is risky” or “this manager is good” into numbers you can compare. They protect you from picking a fund purely on raw returns. They help match a fund to your risk tolerance. And they make it easier to see whether you are paying active fees for passive-like results.
Cons: They are backward-looking and can change quickly. They depend on the benchmark, the period and the data provider. They are unreliable when R-squared is low. Beta treats upside and downside the same, and alpha can be inflated by a short, lucky window.
The sensible way to use them is as a filter and a conversation starter, never as a verdict.
What is the final takeaway on alpha and beta in mutual funds?
Beta tells you what kind of ride you are buying, and alpha tells you whether the person driving is worth the fee. A high alpha is attractive only when it is consistent, measured against the right benchmark and backed by a sensible portfolio. A high beta is neither good nor bad, and it is right only when it fits your horizon and your ability to sit through a fall.
If you remember one thing, make it this: do not judge a fund by returns alone. Check beta for suitability, check alpha for skill, confirm both with R-squared, Sharpe and downside capture, and match the result to your own goal. If you would like a second pair of eyes on your current funds, the Techolic team is happy to help you review them against these measures.
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. The numerical examples in this article are illustrative assumptions and not forecasts or recommendations of any scheme.
Frequently Asked Questions
What is a good alpha for a mutual fund?
Any consistently positive alpha is good, because it means the manager added value after adjusting for risk. As a rough guide, even 1 to 2 percentage points a year over five years or more is meaningful in a hard-to-beat category like large cap. A bigger number over one short period is far less reliable than a modest number that holds across several years.
What is a good beta for a mutual fund?
There is no single good beta. A beta of 1 means the fund moves with its benchmark, below 1 means it moves less, and above 1 means it moves more. Choose the beta that fits your goal and your ability to tolerate falls. A conservative investor with a short horizon should lean toward lower beta, and a long-term investor can accept higher beta.
Can alpha be negative in a mutual fund?
Yes. Negative alpha means the fund returned less than its risk level and the market’s performance would have predicted. It is common in individual years and is not alarming on its own. Persistent negative alpha over five years or more suggests the fund is not earning its fee.
Can beta be negative?
Mathematically yes, but it is rare for equity mutual funds. A negative beta would mean the fund tends to move opposite to its benchmark. Most diversified equity funds have a positive beta between about 0.7 and 1.3 against their benchmark.
What is the difference between alpha and the Sharpe ratio?
Alpha measures excess return relative to a benchmark after adjusting for beta. The Sharpe ratio measures return per unit of total volatility without reference to a benchmark. Alpha asks whether the manager beat the market on a risk-adjusted basis, and Sharpe asks how efficiently the fund turned risk into return. Using both gives you a fuller picture.
Is a high beta fund better for long-term SIP investing?
Not automatically. A high-beta fund can compound faster in long rising markets, but its deeper falls test your discipline. If you would stay invested through a 30% decline, a higher beta may suit a long horizon. If you would stop your SIP, a lower beta fund you can hold through the whole cycle will serve you better.
Do index funds have alpha?
Not in the usual sense. An index fund aims to replicate its index, so its beta is close to 1 and its alpha hovers around zero, usually slightly negative because of the expense ratio and tracking error. The goal of an index fund is to deliver market returns at low cost, not to beat the market.
How often should I check the alpha and beta of my funds?
Review them once or twice a year, along with the rest of your portfolio. Checking monthly adds noise without insight, because both numbers move with the data window. Check sooner if the fund manager changes, the fund’s strategy shifts or its size grows sharply.