Since 1 April 2021, there has been no “dividend option” in Indian mutual funds. SEBI renamed it Income Distribution cum Capital Withdrawal (IDCW), and the new name admits what the old one hid: the money that lands in your bank account can include your own capital. Even so, many retirees still pick the dividend plan, because a credit that arrives without any action feels like a salary.
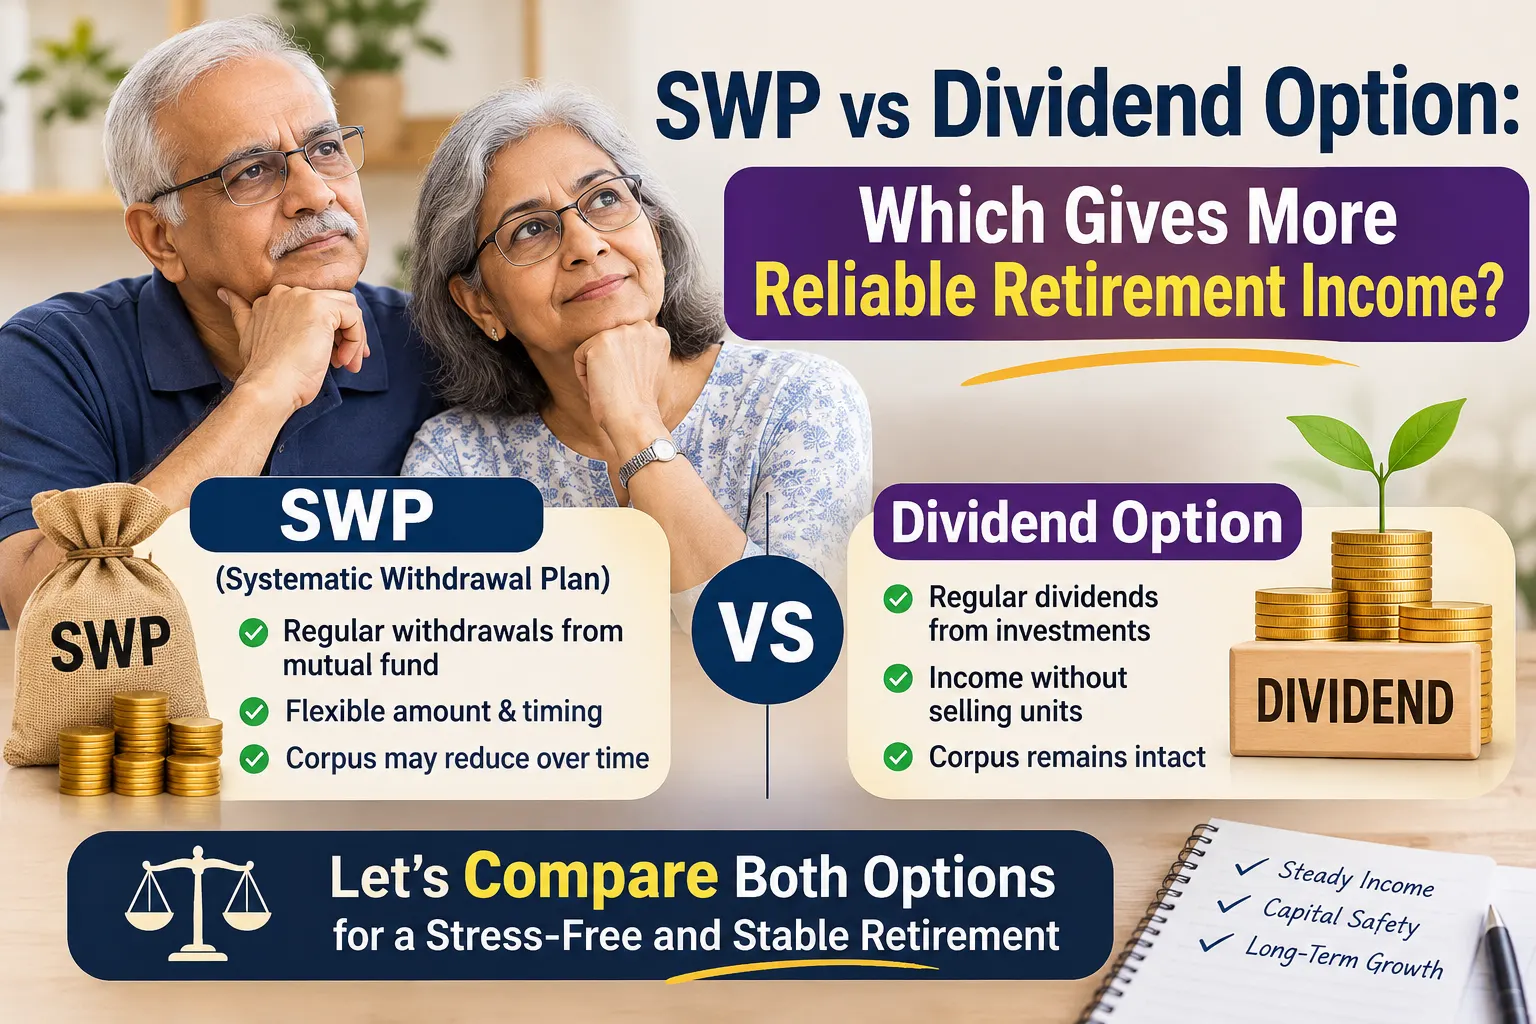
The SWP vs dividend option decision comes down to one question: who controls your retirement income, you or the fund house? A Systematic Withdrawal Plan (SWP) lets you set the amount and the date. The IDCW option leaves both to the fund’s discretion. This guide walks through how each one works, how each is taxed in FY 2026-27, what a ₹1 crore corpus looks like under both, and how to set up monthly income that you can actually plan your life around.
What Is the Dividend Option in a Mutual Fund and How Does It Pay You?
The dividend option is now called the IDCW option. Under it, the fund periodically declares a payout from its distributable surplus. You can take the payout in your bank account (IDCW payout) or have it reinvested in the same scheme (IDCW reinvestment). Either way, it counts as income in your hands.
Where does an IDCW payout actually come from?
The surplus can include dividends and interest the fund earned, profits booked from selling holdings, and, when those fall short, a slice of the money investors put in. That last part is the “capital withdrawal” in the name.
Here is what it does to your holding, using simple illustrative numbers. You own 1,000 units at a NAV of ₹50, so your holding is worth ₹50,000. The fund declares ₹2 per unit. You receive ₹2,000, and the NAV drops to about ₹48, so your units are now worth ₹48,000. Your total wealth has not changed. You have only moved ₹2,000 from the fund to your bank account, and that ₹2,000 is now taxable.
Is an IDCW payout guaranteed?
No. The fund house decides whether to declare a payout, how much, and when. No surplus means no payout, and a bigger payout does not mean a better fund. For anyone running a household on this money, that is the central weakness.
What Is an SWP and How Does It Work?
A Systematic Withdrawal Plan is an instruction you give the fund house: redeem enough units to pay me a fixed amount on a fixed date. You choose the fund, the amount, and the frequency (monthly or quarterly). Your money stays in the growth option, and each withdrawal sells units at that day’s NAV.
Three mechanics matter for retirees:
- Units are sold, not NAV reduced. Your unit count falls with each withdrawal while the remaining units keep moving with the market.
- Only the gain portion is taxed. Every withdrawal is part original cost and part profit. Tax applies to the profit part only.
- FIFO applies. The oldest units are treated as sold first, which decides the holding period and the tax rate on each withdrawal.
You can pause, stop, or change the amount whenever you like. Many equity-oriented schemes charge an exit load on units redeemed within a year of purchase, so check the scheme document before you start.
SWP vs Dividend Option: How Do the Two Compare Side by Side?
- Who decides the amount: With an SWP, you do. With IDCW, the fund house does.
- Predictability: An SWP credits the same amount on the same date. IDCW can be irregular, smaller than expected, or nil.
- Source of the cash: An SWP comes from redeeming units. IDCW comes from distributable surplus, which may include your capital.
- Effect on your holding: An SWP reduces your units. IDCW reduces the NAV and leaves units unchanged.
- What gets taxed: In an SWP, only the gain part of each withdrawal. In IDCW, the entire payout.
- TDS for resident investors: No TDS on SWP redemptions. IDCW attracts 10% TDS once it exceeds ₹10,000 from one fund house in a financial year (20% if PAN is not on record).
- Flexibility: An SWP can be stepped up, paused, or resized. IDCW cannot be dialled up or down.
- Capital erosion: Both can eat into capital. An SWP shows it openly in your unit count, while IDCW hides it inside a falling NAV.
Which Gives More Reliable Retirement Income: SWP or Dividend Option?
For most retirees, SWP wins on reliability, and it is not a close call. Reliable income has two parts: the amount and date must be predictable, and the corpus must last as long as you do. In the SWP vs dividend option contest, the SWP delivers the first part by design, because you set it. IDCW cannot promise either part.
There is a common belief that IDCW is gentler on capital because you are “not selling anything”. The NAV drop after every payout shows otherwise. You are withdrawing money either way. With an SWP you choose how much, and with IDCW someone else does.
Worth remembering: An SWP guarantees the date and amount of your income. It does not guarantee that your corpus will last. That depends on how much you withdraw and the order in which returns arrive. The next sections deal with exactly that.
How Are SWP and IDCW Taxed Differently?
The rules below are for a resident individual under FY 2026-27 rules. “Equity-oriented” means a fund holding at least 65% in equity. Tax laws change, so verify the current position before you act.
How is IDCW taxed?
IDCW is added to your income and taxed at your slab rate, with no concession and no exemption. Reinvested IDCW is taxed too. The fund house deducts 10% TDS once your IDCW from it crosses ₹10,000 in a year. That is only an advance deposit; your final tax depends on your slab, and any excess is refundable when you file your return.
How is an SWP from an equity-oriented fund taxed?
Each withdrawal is a redemption, and only the profit portion is taxable. Units held up to 12 months attract short-term capital gains tax at 20%. Units held longer attract long-term capital gains tax at 12.5%, but only on total gains above ₹1.25 lakh in a financial year. Budget 2026 left these rates unchanged.
How is an SWP from a debt or hybrid fund taxed?
For debt fund units bought on or after 1 April 2023, gains are taxed at your slab rate regardless of how long you hold them. Hybrid funds depend on equity exposure: those with at least 65% in equity follow equity rules, while funds in the middle range follow a different rule with a longer holding period and no ₹1.25 lakh exemption. Always confirm your scheme’s tax classification with the fund house. Even in the slab-rate case, only the gain part of each withdrawal is taxed.
Does the Section 87A rebate change the SWP vs dividend option comparison?
It narrows the tax gap for some retirees. Under the new tax regime, the rebate wipes out slab-rate tax if your total income is within ₹12 lakh, and IDCW is slab-rate income. The rebate does not apply to special-rate capital gains such as equity LTCG and STCG. So a retiree with little other income may owe little or no tax on IDCW, though TDS is still deducted first and has to be claimed back.
That affects the tax comparison, but not the reliability comparison. An IDCW payout that arrives late, small, or not at all is just as unreliable at a zero tax rate.
How Does the Math Look? A Worked Example With ₹1 Crore
These numbers are illustrations built on assumptions, not forecasts or promises.
The setup: A ₹1 crore corpus sits in an equity-oriented hybrid fund that has already been held for over a year. The SWP pays ₹30,000 a month (₹3.6 lakh a year, a 3.6% starting rate) and steps up 6% a year to track inflation. The fund is assumed to return a steady 8% a year. For simplicity, we assume the starting cost equals ₹1 crore. In real life your cost is usually lower than your current value, so your taxable share would be higher than shown.
Year 1: Withdrawals of ₹3.6 lakh contain only about ₹15,000 of gains, inside the ₹1.25 lakh exemption. SWP tax: nil.
Year 10: Withdrawals are about ₹6.1 lakh a year, of which roughly ₹3.2 lakh is gain. SWP tax: about ₹25,000.
Year 20: Withdrawals are about ₹10.9 lakh a year, with roughly ₹8.5 lakh of gain. SWP tax: about ₹94,000.
Now put the same cash flow through the IDCW option, purely as a tax comparison:
Year 1, IDCW of ₹3.6 lakh: About ₹75,000 tax at a 20% slab and about ₹1.12 lakh at 30% (cess included), against nil for the SWP.
Year 10, IDCW of ₹6.1 lakh: About ₹1.27 lakh at a 20% slab, against about ₹25,000 for the SWP.
In practice, no IDCW fund will pay this schedule on cue, which is the whole point. The SWP can.
What Is Sequence-of-Returns Risk and Why Does It Matter for an SWP?
Two retirees can earn the same average return over 30 years and end up in very different places. The difference is the order in which the good and bad years arrive.
Run the example above for 30 years at an average of 8% a year, with three outcomes:
Steady returns: About ₹2 crore is still invested at year 30.
Three poor years at the start (-15%, -5%, +5%), strong years later, same 8% average: The corpus falls to about ₹65 lakh by year 25 and runs dry in the final year.
The same three poor years at the end instead: About ₹3.27 crore remains.
When markets fall early, your fixed withdrawals sell more units at low prices, and those units cannot recover. That is why the first five years of retirement matter most, and why a rigid SWP set at an aggressive rate can fail even when long-run returns look fine.
What Withdrawal Rate Is Reasonable for an Indian Retiree?
The famous 4% rule comes from US data and US inflation. India’s long-run inflation has run higher, so India-focused studies and most practitioners start more conservatively, at roughly 3% to 3.5% of the corpus in year one, then raise the amount with inflation. This is a planning guide, not a guarantee.
In rupee terms, ₹1 crore supports about ₹25,000 to ₹29,000 a month, which means you need a corpus of roughly 29 to 33 times your first-year expenses. If you also have an EPF or PPF maturity, an NPS annuity, or a pension, those carry part of the load, and your portfolio can work a little less hard. At Techolic, we treat 3% to 3.5% as a starting point and then adjust it for other income, medical costs, and the goals you still want to fund.
Withdrawing 6% to 8% because your fund returned 12% in the past is the single most common way an SWP goes wrong.
How Should You Set Up an SWP So the Income Stays Reliable?
Build two buckets. Keep the next two years of expenses in a stable, low-volatility fund. Keep the rest in a growth-oriented fund. Run the SWP from the stable bucket and refill it once a year from the growth bucket when markets allow.
Choose the fund for its job. A hybrid fund with a real debt cushion suits withdrawals better than a pure equity fund. Look at expense ratio and consistency, not the IDCW yield.
Start low. Begin at 3% to 3.5% and step up with inflation. In a year when markets fall sharply, consider skipping the step-up.
Watch holding periods and exit load. For equity-oriented funds, units held beyond 12 months get the better tax treatment.
Align the SWP date with your bills. Set it a few days before your regular expenses fall due.
Review once a year. Check the corpus, the withdrawal rate, and your tax position. Checking monthly only breeds anxiety.
At Techolic, we start every retirement-income plan from your expense budget and not from a fund list. The bucket sizes, the starting rate, and the fund mix all follow from that number.
When Does the Dividend Option Still Make Sense?
It has a narrow place. If the payout is a bonus on top of your real income and not the income itself, IDCW’s irregularity does not hurt. It may also suit someone in a low tax bracket under the rebate who values an automatic credit. And some investors simply find it easier not to “sell” anything.
Treat that as convenience, not strategy. If you want a regular credit without a monthly decision, a quarterly SWP does the same job with far more control.
What Are the Pros and Cons of Each Option?
SWP, pros: You set the amount and date. Only gains are taxed. No TDS on redemptions for residents. It can be stepped up or paused.
SWP, cons: The corpus can run down if you withdraw too much. A sharp market fall early on can damage the plan. It needs a yearly review.
IDCW, pros: No instruction to place each month. Some retirees find it psychologically easier. Can suit very small top-ups.
IDCW, cons: Payout is not assured. The whole amount is taxable. TDS is deducted above ₹10,000. NAV falls after each payout. It can quietly return your own capital.
What Are the Common Mistakes Retirees Make With SWP and IDCW?
- Reading a high IDCW payout as a high return. A larger payout means a larger NAV drop, not better performance.
- Choosing IDCW to “save tax”. It usually does the opposite, since the full payout is taxed.
- Setting the SWP rate from past returns. Base it on a conservative starting rate and your actual expenses.
- Running an SWP from a pure equity fund with no cash buffer. A bad first two years can force you to sell at the worst time.
- Ignoring FIFO and exit load. Recently bought units may cost you more to redeem.
- Forgetting the tax return. SWP gains must be reported as capital gains, and IDCW with its TDS must be reported as income.
- Stepping up blindly every year. Inflation matters, but so does what your portfolio can support after a falling market.
If you are unsure about any of these, we at Techolic can run your numbers across different fund types and withdrawal rates before you commit.
FAQs – Frequently Asked Question
What is the main difference in SWP vs dividend option for retirees?
With an SWP, you decide the amount and date, and only the gain portion of each withdrawal is taxed. With the dividend (IDCW) option, the fund house decides the payout, which is not assured and is fully taxable at your slab rate.
Is SWP better than IDCW for monthly income?
For most retirees, yes. An SWP gives a predictable amount on a fixed date, while IDCW can vary or stop. The SWP still requires a sensible withdrawal rate so the corpus lasts.
Is IDCW guaranteed income?
No. The fund declares IDCW at its discretion from distributable surplus. The amount and timing are not assured, and payouts can include part of your own capital.
Is an SWP taxable?
Yes, but only on the profit part of each withdrawal. Equity-oriented fund gains are taxed at 20% (short-term) or 12.5% above ₹1.25 lakh a year (long-term). Debt fund gains on units bought on or after 1 April 2023 are taxed at your slab rate.
Is TDS deducted on SWP withdrawals?
Not for resident investors on redemptions. TDS applies to IDCW: 10% once it exceeds ₹10,000 from one fund house in a financial year (20% without PAN).
How much can I withdraw every month through an SWP?
A common conservative starting point is 3% to 3.5% of your corpus a year, which is about ₹25,000 to ₹29,000 a month on ₹1 crore, raised with inflation. Your own number depends on other income, expenses, and your fund mix.
Can I switch from the IDCW option to an SWP?
Usually you move to the growth option of the same fund and start the SWP there. Moving between options can be treated as a redemption, so check the tax and exit load impact with the fund house or your advisor first.
Is the IDCW option the same as the old dividend option?
Yes. SEBI renamed the dividend option as IDCW from 1 April 2021 to make clear that payouts can include your own capital.
What Is the Bottom Line on SWP vs Dividend Option?
If you want income you can plan around, choose the SWP. It gives you control over the amount and the date, and it taxes only your gains. The dividend option gives you convenience, but the fund house is in charge of your cash flow.
An SWP works only if the withdrawal rate is realistic, the fund fits the job, and you keep a cash buffer for the early years. If you want help building that plan, we at Techolic can map your expenses, your other income, and your corpus into a withdrawal plan you can stick with.